Showing posts with label Subscriber Letter. Show all posts

Tuesday, July 17, 2012

Mid-Year Update of QE Subscriber Letter Trade Idea Results


I don't often discuss trade idea results from the subscriber letter here on the blog. The last time I did was in January. 2012 so far has been a very strong year and many subscribers have written to say they’ve benefitted.  The reason I don’t often post results is that while I've always tracked trade ideas in the subscriber letter, it isn't the main focus of the service. I don't consider Quantifiable Edges to be a stock picking service. I consider it one where traders can gain market and trading knowledge through the published research, systems, and tools. The objective is to provide tools and instruction to help traders improve their own trading and results.

But the published trade ideas have done quite well. In fact, only 1 month of the last 21 months have the trade ideas failed to add up to positive gains.  2012 so far has seen positive gains every month.  And the Catapult trades, which make up the CBI, have not had a single losing cluster (or group of trades) in over 3 years.

I don't suggest position sizes, and I would never suggest that the trade ideas represent any kind of complete portfolio strategy. They are what they are - ideas about certain stocks or ETFs that have historically provided a statistical edge.

It is important to note that all of the trade ideas are in either ETFs or in highly liquid large cap stocks (almost exclusively S&P 100 components). I do this so that executing trades and getting fills at reasonable prices is not an issue. I think traders feel the most frustrating aspect of following trade ideas offered by some services is not being able to get into or out of the trades that they suggest at a similar price. I’ve addressed this problem with limit prices and highly liquid securities.

Some of my goals with a gold subscription have always been to help people improve their trading through the use of quantified research, and while doing so to help them offset the costs of the subscription by offering easy-to-execute trade ideas with a long-term positive profit expectancy. To date I believe Quantifiable Edges has succeeded in doing this.

As I did 6 months ago, I have again broken down the results by year.  For tracking purposes I only count trades after they have been closed out. With most trades being of the swing variety this doesn’t normally skew results much. But it does occasionally when a big trades lasts over a month or year-end.
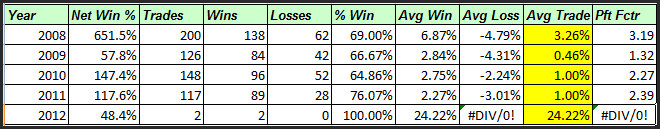
Below are the results by year.


Stats have been strong across the board in 2012, with “% win” and “profit factor” really standing out.  I've become a bit more selective the last year and a half, which has led to a small dip in the number of trade ideas, but has also seemed to help with winning %.

For those that are interested, the complete list of trade ideas from 2008 - present can be downloaded from the systems page of the members’ section of Quantifiable Edges. (Available to paid and trial subscribers.) And with the full archive of subscriber letters available on the site, gold subscribers can also go back and see what I wrote about any trade and my reasons for entry and exit when it happened.

With a subscription to Quantifiable Edges I try and provide traders with ideas and instruction to improve their trading. These ideas may come in the form of previously published studies identified by the Quantifinder, or they may be something I discuss in the current subscriber letter, or perhaps it's a webinar focused on a certain trading approach or indicator, or any other number of tools that I've designed and made available. (For a more complete list of tools, see the "Using Quantifiable Edges" series of posts.) The trade ideas found in the subscriber letter are examples of how I put these tools and ideas to work. While past performance is not necessarily indicative of future results, over the long run they’ve performed well enough that many subscribers have used them for their benefit.

For more information on a gold subscription, or to subscribe, click here.

Lastly, below is the explanations and disclaimer from the Trade Ideas Results Spreadsheet.


All trade ideas ever tracked in the Quantifiable Edges Subscriber Letter may be found on this spreadsheet. I don’t suggest position sizes. The primary reason for this is I’m not acting as a financial advisor. I don’t feel it is appropriate to suggest allocation sizes without understanding someone’s financial situation and risk tolerance. Even for my own trading I run different portfolios with different levels of aggressiveness. For instance, my most aggressive may use options to sometimes get 300-400% leveraged. Other portfolios on the other hand normally take much more conservative stances and some rarely reach or exceed 100% exposure.


Since I don’t suggest position sizes this is should not be considered a performance report, but rather a trade idea scorecard. Therefore, no matter how objective I try to be the reporting of the results is always going to be skewed depending on how you approach the trades. For instance, I always recommend scaling into the Catapult positions in 3 parts, whereas the “System” trades (whatever system I unveil other than Catapult) are normally one entry. The “Index” trades I normally recommend scaling into as well. For my own trading I trade much larger size with the index trades than any of the individuals. I also control my exposure by limiting the total amount invested per day. As I mentioned, this will vary depending on the account I’m trading. My most aggressive account I may put in up to 100%/day and get heavily leveraged using options. A more conservative account may max out at 15%-20% per day.


It’s unlikely anyone would have taken all of the trades with equal amounts, so personal results would vary greatly depending on the trader’s approach. Simply adding up the results of the individual triggers as I do is an admittedly poor representation of returns. A net positive or negative does not necessarily mean a person following the ideas would have made or lost money during the period measured. And the sum total is certainly not representative of what a portfolio would return. 


Feel free to contact me at support @ QuantifiableEdges.com if you have any questions.


As required by the NFA: Except where otherwise specifically stated, all trades are based on hypothetical or simulated trading. Hypothetical or simulated performance results have certain inherent limitations. Unlike an actual performance record, simulated results do not represent actual trading. Also, since the trades have not actually been executed, the results may have under-or-over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profits or losses similar to those shown. Commissions, fees, and slippage have not been included. This is neither a solicitation to buy/sell securities or listed options.

Friday, January 6, 2012

2011 (and prior) Trade Idea Results from the QE Subscriber Letter

I don't often discuss trade idea results from the subscriber letter here on the blog. The last time I did was in June. But 2011 was another solid year and I thought it would be worth mentioning in the hope that Quantifiable Edges could help traders improve their results in 2012. I don’t post results regularly because while I've always tracked trade ideas in the subscriber letter, it isn't the main focus of the service. I don't consider Quantifiable Edges to be a stock picking service. I consider it one where traders can gain market and trading knowledge through the published research, systems, and tools. The objective is to provide tools and instruction to help traders improve their own trading and results.

But the published trade ideas have done quite well. In fact, during 2011 October was the only month where the trade ideas failed to add up to positive gains. I've had several letters from subscribers lately telling me they've done quite well following certain ideas and that is always nice to hear.

I don't suggest position sizes, and I would never suggest that the trade ideas represent any kind of complete portfolio strategy. They are what they are - ideas about certain stocks or ETFs that have historically provided a statistical edge.

It is important to note that all of the trade ideas are in either ETFs or in highly liquid large cap stocks (almost exclusively S&P 100 components). I do this so that executing trades and getting fills at reasonable prices is not an issue. I think traders feel the most frustrating aspect of following trade ideas offered by some services is not being able to get into or out of the trades that they suggest at a similar price. I’ve addressed this problem with limit prices and highly liquid securities.

Some of my goals with a gold subscription have always been to help people improve their trading through the use of quantified research, and while doing so to help them offset the costs of the subscription by offering easy-to-execute trade ideas with a long-term positive profit expectancy. To date I believe Quantifiable Edges has succeeded in doing this.

Today I broke the results down by year. Amazingly, for the 2nd year in a row the trade ideas during 2011 averaged a 1.00% gain per trade idea. I also listed all of December and January’s (so far) results below so that traders could see some examples. For tracking purposes I only count trades after they have been closed out. With most trades being of the swing variety this doesn’t normally skew results much. But we did just close out a big winner that was entered in November so 2012 results are overstated while 2011 are a bit understated due to that particular trade. First let’s look at the results by year:


Now recent trade ideas:


For those that are interested, the complete list of trade ideas from 2008 - present can be downloaded from the systems page of the members’ section of Quantifiable Edges. (Available to paid and trial subscribers.) And with the full archive of subscriber letters available on the site, gold subscribers can also go back and see what I wrote about any trade and my reasons for entry and exit when it happened.

With a subscription to Quantifiable Edges I try and provide traders with ideas and instruction to improve their trading. These ideas may come in the form of previously published studies identified by the Quantifinder, or they may be something I discuss in the current subscriber letter, or perhaps it's a webinar focused on a certain trading approach or indicator, or any other number of tools that I've designed and made available. (For a more complete list of tools, see the "Using Quantifiable Edges" series of posts.) The trade ideas found in the subscriber letter are examples of how I put these tools and ideas to work. While past performance is not necessarily indicative of future results, over the long run they’ve performed well enough that many subscribers have used them for their benefit.

For more information on a gold subscription, or to subscribe, click here.

Lastly, below is the explanations and disclaimer from the Trade Ideas Results Spreadsheet.


All trade ideas ever tracked in the Quantifiable Edges Subscriber Letter may be found on this spreadsheet. I don’t suggest position sizes. The primary reason for this is I’m not acting as a financial advisor. I don’t feel it is appropriate to suggest allocation sizes without understanding someone’s financial situation and risk tolerance. Even for my own trading I run different portfolios with different levels of aggressiveness. For instance, my most aggressive may use options to sometimes get 300-400% leveraged. Other portfolios on the other hand normally take much more conservative stances and some rarely reach or exceed 100% exposure.


Since I don’t suggest position sizes this is should not be considered a performance report, but rather a trade idea scorecard. Therefore, no matter how objective I try to be the reporting of the results is always going to be skewed depending on how you approach the trades. For instance, I always recommend scaling into the Catapult positions in 3 parts, whereas the “System” trades (whatever system I unveil other than Catapult) are normally one entry. The “Index” trades I normally recommend scaling into as well. For my own trading I trade much larger size with the index trades than any of the individuals. I also control my exposure by limiting the total amount invested per day. As I mentioned, this will vary depending on the account I’m trading. My most aggressive account I may put in up to 100%/day and get heavily leveraged using options. A more conservative account may max out at 15%-20% per day.


It’s unlikely anyone would have taken all of the trades with equal amounts, so personal results would vary greatly depending on the trader’s approach. Simply adding up the results of the individual triggers as I do is an admittedly poor representation of returns. A net positive or negative does not necessarily mean a person following the ideas would have made or lost money during the period measured. And the sum total is certainly not representative of what a portfolio would return.


Feel free to contact me at support @ QuantifiableEdges.com if you have any questions.


As required by the NFA: Except where otherwise specifically stated, all trades are based on hypothetical or simulated trading. Hypothetical or simulated performance results have certain inherent limitations. Unlike an actual performance record, simulated results do not represent actual trading. Also, since the trades have not actually been executed, the results may have under-or-over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profits or losses similar to those shown. Commissions, fees, and slippage have not been included. This is neither a solicitation to buy/sell securities or listed options.

Saturday, June 4, 2011

Recent & Long-Term Subscriber Letter Trade Idea Results

I don't often discuss trade idea results from the subscriber letter here on the blog. In fact, I checked and it looks like the last time I did so was a little over two years ago. I used to do it more often, but I fell out of the habit. Also while I've always posted and tracked trade ideas in the subscriber letter, it isn't the main focus of the service. I don't consider Quantifiable Edges to be a stock picking service. I consider it one where traders can gain market and trading knowledge through the published research, systems, and tools. The objective is to provide tools and instruction to help traders improve their own trading and results.

But the published trade ideas have done quite well. In fact, May marked the 8th month in a row where the trade ideas added up to positive gains. I've had several letters from subscribers lately telling me they've done quite well either following certain ideas or trading the systems, and explaining to me how they approach the trades.

I don't suggest position sizes, and I would never suggest that the trade ideas represent any kind of complete portfolio strategy. They are what they are -ideas about certain stocks or ETFs that have historically provided a statistical edge.

All of the trade ideas are in either highly liquid ETFs or in highly liquid large cap stocks (almost exclusively S&P 100 components). I do this so that executing trades and getting fills at reasonable prices is not an issue. I think the most frustrating aspect of following trade ideas offered by another person (not that I'm encouraging that, but I know it happens) is not being able to get into or out of the trades that they suggest at a similar price. I’ve addressed this problem with limit prices and highly liquid securities.

With a subscription to Quantifiable Edges I try and provide traders with ideas and instruction to improve their trading. These ideas may come in the form of previously published studies identified by the Quantifinder, or they may be something I discuss in the current subscriber letter, or perhaps it's a webinar focused on a certain trading approach or indicator, or any other number of tools that I've designed and made available.  (For a more complete list of tools, see the "Using Quantifiable Edges" series of posts.) The trade ideas found in the subscriber letter are examples of how I put these tools and ideas to work. While past performance is not necessarily indicative of future results, over the long run they’ve performed well enough that many subscribers have utilized them and easily paid for their subscriptions with the profits.

The blog is free. But what I post here is only the tip of the iceberg.

My goal with a gold subscription has always been to help people improve their trading through the use of quantified research, and while doing so to help them offset the costs of the subscription by offering easy-to-execute trade ideas with a long-term positive profit expectancy. To date I believe Quantifiable Edges has succeeded in doing this. I’d encourage anyone who enjoys the blog but hasn’t yet tried a subscription to do so.

Today I broke the results down by year. I also listed all of May’s trade below so that traders could see some examples. And of course with the full archive of subscriber letters available on the subscriber site, you can go back and see what I wrote about any trade and my reasons for entry and exit when it happened.  First lets look at the results by year:


Now May’s trade ideas:


For those that are interested, the complete list of trade ideas from 2008 - 2011 can be downloaded from the systems page of the members’ section of Quantifiable Edges. (Available to paid and trial subscribers.)

For more information on a gold subscription, or to subscribe, click here.

Lastly, below is the explanations and disclaimer from the Trade Ideas Results Spreadsheet.


All trade ideas ever tracked in the Quantifiable Edges Subscriber Letter may be found on this spreadsheet. I don’t suggest position sizes. The primary reason for this is I’m not acting as a financial advisor. I don’t feel it is appropriate to suggest allocation sizes without understanding someone’s financial situation and risk tolerance. Even for my own trading I run different portfolios with different levels of aggressiveness. For instance, my most aggressive may use options to sometimes get 300-400% leveraged. Other portfolios on the other hand normally take much more conservative stances and some rarely reach or exceed 100% exposure.

Since I don’t suggest position sizes this is should not be considered a performance report, but rather a trade idea scorecard. Therefore, no matter how objective I try to be the reporting of the results is always going to be skewed depending on how you approach the trades. For instance, I always recommend scaling into the Catapult positions in 3 parts, whereas the “System” trades (whatever system I unveil other than Catapult) are normally one entry. The “Index” trades I normally recommend scaling into as well. For my own trading I trade much larger size with the index trades than any of the individuals. I also control my exposure by limiting the total amount invested per day. As I mentioned, this will vary depending on the account I’m trading. My most aggressive account I may put in up to 100%/day and get heavily leveraged using options. A more conservative account may max out at 15%-20% per day.

It’s unlikely anyone would have taken all of the trades with equal amounts, so personal results would vary greatly depending on the trader’s approach. Simply adding up the results of the individual triggers as I do is an admittedly poor representation of returns. A net positive or negative does not necessarily mean a person following the ideas would have made or lost money during the period measured. And the sum total is certainly not representative of what a portfolio would return.

Feel free to contact me at support@QuantifiableEdges.com if you have any questions.

As required by the NFA: Except where otherwise specifically stated, all trades are based on hypothetical or simulated trading. Hypothetical or simulated performance results have certain inherent limitations. Unlike an actual performance record, simulated results do not represent actual trading. Also, since the trades have not actually been executed, the results may have under-or-over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profits or losses similar to those shown. Commissions, fees, and slippage have not been included. This is neither a solicitation to buy/sell securities or listed options.

Tuesday, May 5, 2009

Subscriber Letter Trade Idea Results For April

April was a very quiet month as far as tracked trade ideas for the Quantifiable Edges Subscriber Letter. In fact it was the quietest. There were only 5 trade ideas that were filled. Four of them were index trades and the other one was a system trade plucked from our nightly “systems triggers” sheet. There was one Catapult that triggered but did not receive a fill due to a gap up the next morning that never closed. A big part of why April was so quiet, in fact, was that the market had several unfilled gaps in the direction of our trade ideas. So while only 5 trade ideas filled and were tracked in the Letter, at least 8 others went unfilled. While this occasionally happens, it’s unusual to see it to the extent that occurred in April. More active or aggressive traders could also have plucked ideas from the systems triggers sheet, which typically has at least a few triggers listed each night. Since there were only 5 filled trade ideas, I’ve listed them all below along with the summary stats. (I typically only post the summary stats in the blog and reserve the full list for the Letter.) First, of course, the usual caveats and explanations.

I don’t suggest position sizes. The primary reason for this is I’m not acting as a financial advisor. I don’t feel it is appropriate to suggest allocation sizes without understanding someone’s financial situation and risk tolerance. Even for my own trading I run different portfolios with different levels of aggressiveness. For instance, my most aggressive portfolio is my IRA. Here I may use options to sometimes get 400-500% leveraged. Other portfolios on the other hand normally take much more conservative stances and some rarely reach or exceed 100% exposure.

Since I don’t suggest position sizes this is should not be considered a performance report, but rather a trade idea scorecard. Therefore, no matter how objective I try to be the reporting of the results is always going to be skewed depending on how you approach the trades. For instance, I always recommend scaling into the Catapult positions in 3 parts, whereas the “System” trades (whatever system I unveil other than Catapult) are normally one entry. The “Index” trades I normally recommend scaling into as well. For my own trading I trade much larger size with the index trades than any of the individuals. I also control my exposure by limiting the total amount invested per day. As I mentioned, this will vary depending on the account I’m trading. My most aggressive account I may put in up to 100%/day and get heavily leveraged using options. A more conservative account may max out at 15%-20% per day.


It’s unlikely anyone would have taken all of the trades with equal amounts, so personal results would vary greatly depending on the trader’s approach. Simply adding up the results of the individual triggers as I do below is an admittedly poor representation of returns. A net positive or negative does not necessarily mean a person following the ideas would have made or lost money during the period measured. And the sum total is certainly not representative of what a portfolio would return. All that aside, below are April’s results (click table to enlarge):


And the individual trades (click table to enlarge):


If you haven’t checked out the gold membership area yet, then click here to sign up for a free trial (only a name and email address required). It’s not just trade ideas. It contains research far beyond the blog as well as members-only charts, systems (with code included), and custom indicators.

Friday, April 24, 2009

Subscriber Letter Trade Results for March

Between vacation the 1st week in April and taxes the 2nd week it’s taken me forever to finalize the March trade results, but they’re finally here. March was the 1st difficult month the Letter has had since last August. There were 2 main culprits – Catpults and Index trades.

The Catapult trades had their worst bout in a long time. The primary culprit was the single worst trade in the history of the system. As I’ll describe below, the results are just a scorecard and not a portfolio return. The Catapult trades are normally scaled into in 3 lots. I always just list the gain/loss of each lot rather than slicing the results of those that only had one lot on. Since I don’t suggest allocation sizes it hardly matters, but listing each lot can exaggerate results sometimes. In October for instance, the results were exaggerated upwards. This month, downwards. The net additive results of all the Catapult trades was a loss of about 17% on 21 lots – or about -0.8% per lot. The single worst trade I referred to above had 3 lots active and they accounted for a loss of 58%.

To be fair, it wasn’t just the Catapults that faltered. I was too early to enter some of the index trades as the market collapsed in late February / early March. I also took them off too early in the bounce. The net additive result of the 5 index-sized lots was a loss of 2.8%. These positions are typically scaled into as well and they were in March, with a maximum of 4 on at one point. What I did very right was I avoided trying to short the bounce on the initial thrust off the bottom. Many traders that use overbought/oversold methods mistakenly viewed the initial bounce as a simple “overbought in a downtrend” setup. I discussed extensively in the Subscriber Letter that shorting the initial bounce appeared to be a dangerous proposition. The only short index trade idea I took wasn’t until 3/26 and I exited it with a nice 2.9% profit on 3/30.

Other systems were quiet as I often defer to the Catapults in times of market stress. It didn’t work out this time, but it traditionally has (see last October and November for some outstanding examples). There was only 1 system trade idea tracked outside of the Catapults and it went for a decent gain.

April so far has been much more efficient. There have been only a handful of trade ideas that have received fills and results have been strong so far. I’ll get to those results next month, though. Below are some of the usual caveats and explanations followed by March’s results.

As mentioned above, I don’t suggest position sizes. The primary reason for this is I’m not acting as a financial advisor. I don’t feel it is appropriate to suggest allocation sizes without understanding someone’s financial situation and risk tolerance. Even for my own trading I run different portfolios with different levels of aggressiveness. For instance, my most aggressive portfolio is my IRA. Here I may use options to sometimes get 400-500% leveraged. Other portfolios on the other hand normally take much more conservative stances and some rarely reach or exceed 100% exposure.

Since I don’t suggest position sizes this is should not be considered a performance report, but rather a trade idea scorecard. Therefore, no matter how objective I try to be the reporting of the results is always going to be skewed depending on how you approach the trades. For instance, I always recommend scaling into the Catapult positions in 3 parts, whereas the “System” trades (whatever system I unveil other than Catapult) are normally one entry. The “Index” trades I normally recommend scaling into as well. For my own trading I trade much larger size with the index trades than any of the individuals. I also control my exposure by limiting the total amount invested per day. As I mentioned, this will vary depending on the account I’m trading. My most aggressive account I may put in up to 100%/day and get heavily leveraged using options. A more conservative account may max out at 15%-20% per day.


It’s unlikely anyone would have taken all of the trades with equal amounts, so personal results would vary greatly depending on the trader’s approach. Simply adding up the results of the individual triggers as I do below is an admittedly poor representation of returns. A net positive or negative does not necessarily mean a person following the ideas would have made or lost money during the period measured. And the sum total is certainly not representative of what a portfolio would return. All that aside, below are March’s results (click to enlarge):


Detailed trade by trade results will appear in this weekend’s Subscriber Letter. If you haven’t checked out the gold membership area yet, then click here to sign up for a free trial (only a name and email address required). It’s not just trade ideas. It contains research far beyond the blog as well as members-only charts, systems (with code included), and custom indicators.

Sunday, March 15, 2009

Subscriber Letter Trade Results For February

So I finally got around to putting together the stats for February for the Subscriber Letter and have included them below. There are very few trades that were closed out in February. There were several active ones that didn’t get closed out until March. For simplicity I’ve always just reported the closed trades. I see no point in marking to market at the end of each month and running complex stats. Reason being this is NOT a performance report. No allocation sizes are suggested and the trade ideas are not presented as a portfolio, but rather a list of actionable ideas that I track. The February results were once again excellent. March got off to a rough start with a couple of individual trades. This week has been good but there’s a decent chance it may have the first negative total since last August. I’m getting ahead of myself, though. Below are some of the usual caveats followed by the February summary results.

As mentioned above, I don’t suggest position sizes. The primary reason for this is I’m not acting as a financial advisor. I don’t feel it is appropriate to suggest allocation sizes without understanding someone’s financial situation and risk tolerance. Even for my own trading I run different portfolios with different levels of aggressiveness. For instance, my most aggressive portfolio is my IRA. Here I may use options to sometimes get 400-500% leveraged. Other portfolios on the other hand normally take much more conservative stances and some rarely reach or exceed 100% exposure.


Since I don’t suggest position sizes this is should not be considered a performance report, but rather a trade idea scorecard. Therefore, no matter how objective I try to be the reporting of the results is always going to be skewed depending on how you approach the trades. For instance, I always recommend scaling into the Catapult positions in 3 parts, whereas the “System” trades (whatever system I unveil other than Catapult) are normally one entry. The “Index” trades I normally recommend scaling into as well. For my own trading I trade much larger size with the index trades than any of the individuals. I also control my exposure by limiting the total amount invested per day. As I mentioned, this will vary depending on the account I’m trading. My most aggressive account I may put in up to 100%/day and get heavily leveraged using options. A more conservative account may max out at 15%-20% per day.


It’s unlikely anyone would have taken all of the trades with equal amounts, so personal results would vary greatly depending on the trader’s approach. Simply adding up the results of the individual triggers as I do below is an admittedly poor representation of returns. A net positive or negative does not necessarily mean a person following the ideas would have made or lost money during the period measured. And the sum total is certainly not representative of what a portfolio would return. All that aside, below are February’s results (click to enlarge):


Detailed trade by trade results will appear in this weekend’s Subscriber Letter. If you haven’t checked out the gold membership area yet, then click here to sign up for a free trial (only a name and email address required). It’s not just trade ideas. It contains research far beyond the blog as well as members-only charts, systems (with code included), and custom indicators.

Thursday, February 5, 2009

Subscriber Letter Trade Results For January

Like December, January was a bit slow for trade ideas. A big reason for this was that there were no Catapult trade ideas that filled. There were several that triggered on 1/20 but the gap up on 1/21 kept them from receiving fills.

I only tracked 2 “system” trades in the Subscriber Letter during January. Subscribers that may trade more aggressively than me can find additional setups almost every night in S&P 500 stocks as well as ETF’s by checking the “System Triggers” page in the members section of the website.

The “Index” trades are typically SPY and QQQQ trades based on the short-term market outlook section of the Letter. The outlook is based on edges identified in my market studies. One tool I use to quantify the different studies is the Aggregator.

Now for the usual caveats and explanations before unveiling the results.


I don’t suggest position sizes. The primary reason for this is I’m not acting as a financial advisor. I don’t feel it is appropriate to suggest allocation sizes without understanding someone’s financial situation and risk tolerance. Even for my own trading I run different portfolios with different levels of aggressiveness. For instance, my most aggressive portfolio is my IRA. Here I may use options to sometimes get 400-500% leveraged. Other portfolios on the other hand normally take much more conservative stances and some rarely reach or exceed 100% exposure.


Since I don’t suggest position sizes this is should not be considered a performance report, but rather a trade idea scorecard. Therefore, no matter how objective I try to be the reporting of the results is always going to be skewed depending on how you approach the trades. For instance, I always recommend scaling into the Catapult positions in 3 parts, whereas the “System” trades (whatever system I unveil other than Catapult) are normally one entry. The “Index” trades I normally recommend scaling into as well. For my own trading I trade much larger size with the index trades than any of the individuals. I also control my exposure by limiting the total amount invested per day. As I mentioned, this will vary depending on the account I’m trading. My most aggressive account I may put in up to 100%/day and get heavily leveraged using options. A more conservative account may max out at 15%-20% per day.

It’s unlikely anyone would have taken all of the trades with equal amounts, so personal results would vary greatly depending on the trader’s approach. All that aside, below are January’s results (click to enlarge):


If you'd like to try out a Quantifiable Edges subscription then click here for a free 1-week trial. (Only a name and email address are required.) For complete subscription information to the Gold package click here.

Tuesday, January 20, 2009

Quantifiable Edges Gold Subscriber Letter 2008 Index Trade Idea Results

While 2008 was an incredibly difficult year for buy and hold, it was an especially good year for the Quantifiable Edges Subscriber Letter. The trade ideas listed in the Letter are generally short-term in nature. They come from either mechanical systems that are published by Quantifiable Edges, our proprietary Catapult system (which is used to measure the CBI), or as index trades through our detailed market analysis and studies. Only large-cap stocks (primarily S&P 100) and highly liquid ETF’s are used for the trade ideas. This helps to assure subscribers wishing to trade some of the ideas that liquidity won’t be a problem.

The trades ideas that are most popular among subscribers are the studies-based index trades. Frequently I will use the Aggregator tool to help time entries and exits.

After several inquiries I have decided to simply show a listing of all the index trades closed in 2008. A few notes:

I typically scale in to index trades. Most often ¼ at a time. Therefore in the listing below you will notice there were times where more than 1 entry was open at once. The max is 4.

These are just trade ideas. I never suggest allocation percentages. A ¼ index position could mean a 5% allocation to one person or a 75% allocation to another (who may eventually get 300% or more leveraged).

The index trade ideas are tracked using either SPY or QQQQ. Some subscribers may use options, futures, inverse or ultra ETF’s or some combination of the above to better suit their trading. I never suggest ultra etf’s in the Subscriber Letter. While I believe they are a worthy trading vehicle and utilize them myself on occasion, I prefer not to use them in the trade ideas section as it could appear I’m simply trying to inflate my results.

Trade ideas are all published in the Subscriber Letter each night. In many cases the exits are also established in the nightly Letter. In response to subscriber feedback, in May I began sending out intraday updates on open positions when appropriate. The intraday updates are sometimes used to set stops or targets or suggest an exit at the close of the day. Intraday updates are NEVER used to suggest new positions.

So while personal results would vary greatly depending on the traders approach to the ideas, below is the complete listing of closed index trade ideas from last February’s inception through the end of 2008 (Summary results shown further down. Commissions not included.):
(click to enlarge)


Past results are not necessarily indicative of future returns. But if you’d like to improve your market timing and think Quantifiable Edges could help then click here for a free 1-week trial. For complete subscription information to the Gold package click here.

Monday, January 12, 2009

Gold Level Subscription Scorecard For December

December was an extremely quiet month for trade ideas. There were only 7 trade ideas closed during the Month. April and July both had 13 trade ideas closed, which was the previous low. This was due to a few reasons.

First, there were several trade ideas that didn’t receive fills. This was primarily due to the market gapping in our direction and not providing an entry opportunity.

Another reason for the low number of “official” trade ideas was the fact that no Catapults triggered. Catapults were plentiful in October and November. Typically 2-3 times each year there will be a decent sized cluster of catapult trades for traders to try and take advantage of.

Lastly, the action itself in December was extremely choppy. The S&P didn’t close in the same direction 3 days in a row at all in December. Several of the strategies are mean-reverting and mean-reverting strategies don’t trigger when you don’t get far from the mean.

Now for my usual caveats and explanations before unveiling the results.

I don’t suggest position sizes. The primary reason for this is I’m not acting as a financial advisor. I don’t feel it is appropriate to suggest allocation sizes without understanding someone’s financial situation and risk tolerance. Even for my own trading I run different portfolios with different levels of aggressiveness. For instance, my most aggressive portfolio is my IRA. Here I may use options to sometimes get 400-500% leveraged. Other portfolios on the other hand normally take much more conservative stances and some rarely reach or exceed 100% exposure.

Since I don’t suggest position sizes this is should not be considered a performance report, but rather a trade idea scorecard. Therefore, no matter how objective I try to be the reporting of the results is always going to be skewed depending on how you approach the trades. For instance, I always recommend scaling into the Catapult positions in 3 parts, whereas the “System” trades (whatever system I unveil other than Catapult) are normally one entry. The “Index” trades I normally recommend scaling into as well. For my own trading I trade much larger size with the index trades than any of the individuals. I also control my exposure by limiting the total amount invested per day. As I mentioned, this will vary depending on the account I’m trading. My most aggressive account I may put in up to 100%/day and get heavily leveraged using options. A more conservative account may max out at 15%-20% per day.

It’s unlikely anyone would have taken all of the trades with equal amounts, so personal results would vary greatly depending on the trader’s approach.
All that aside, below are December’s results (click to enlarge):


In the next couple of days I will post a 2008 summary.

For anyone who would like to trial the Quantifiable Edges Gold Subscription you may do so by simply clicking here.

Wednesday, December 3, 2008

Gold Level Subscription Scorecard For November

While the market once again struggled mightily in November, the volatility made for some nice opportunities for Gold Level Subscribers. Once again this month Quantifiable Edges proprietary Catapult trading strategy which underlies the CBI was best able to take advantage of environment. It was designed to prosper under extreme selling conditions. It has performed exceptionally well the last 2 months with big gains also coming in October.
Before revealing the results, some important notes to review:

I don’t suggest position sizes. The primary reason for this is I’m not acting as a financial advisor. I don’t feel it is appropriate to suggest allocation sizes without understanding someone’s financial situation and risk tolerance. Even for my own trading I run different portfolios with different levels of aggressiveness. For instance, my most aggressive portfolio is my IRA. Here I may use options to sometimes get 400-500% leveraged. Other portfolios on the other hand normally take much more conservative stances and some rarely reach or exceed 100% exposure.

Since I don’t suggest position sizes this is should not be considered a performance report, but rather a trade idea scorecard. Therefore, no matter how objective I try to be the reporting of the results is always going to be skewed depending on how you approach the trades. For instance, I always recommend scaling into the Catapult positions in 3 parts, whereas the “System” trades (whatever system I unveil other than Catapult) are normally one entry. The “Index” trades I normally recommend scaling into as well. For my own trading I trade much larger size with the index trades than any of the individuals. I also control my exposure by limiting the total amount invested per day. As I mentioned, this will vary depending on the account I’m trading. My most aggressive account I may put in up to 100%/day and get heavily leveraged using options. A more conservative account may max out at 15%-20% per day.

It’s unlikely anyone would have taken all of the trades with equal amounts, so personal results would vary greatly depending on the trader’s approach. Still, there was more than ample opportunity to take advantage of the Quantifiable Edges trade ideas in November. With all those caveats in mind, results are listed below and broken down by category.


All of the individual trades are listed in the December 3, 2008 Quantifiable Edges Subscriber Letter. I'll be happy to provide a copy of this Letter to anyone who signs up for a free trial subscription.

Sunday, November 2, 2008

Subscriber Letter Scorecard for October

October may have been the worst month in a long time for the stock market, but it was the best month ever for the Subscriber Letter. The primary strategy responsible for the oversized trading profits were the Catapult trades, which combined comprise the CBI. They also performed well during the January and March selloffs, but suffered an unusually difficult period during the June/July selloff.

Before revealing the results, some important notes:

I don’t suggest position sizes. The primary reason for this is I’m not acting as a financial advisor. I don’t feel it is appropriate to suggest allocation sizes without understanding someone’s financial situation and risk tolerance. Even for my own trading I run different portfolios with different levels of aggressiveness. For instance, my most aggressive portfolio is my IRA. Here I may use options to sometimes get 400-500% leveraged. Other portfolios on the other hand normally take much more conservative stances and some rarely reach or exceed 100% exposure.

Since I don’t suggest position sizes this is should not be considered a performance report, but rather a trade idea scorecard. Therefore, no matter how objective I try to be the reporting of the results is always going to be skewed depending on how you approach the trades. For instance, I always recommend scaling into the Catapult positions in 3 parts, whereas the “System” trades (whatever system I unveil other than Catapult) are normally one entry. The “QE Index” trades I normally recommend scaling into as well. For my own trading I trade much larger size with the index trades than any of the individuals. I also control my exposure by limiting the total amount invested per day. As I mentioned, this will vary depending on the account I’m trading. My most aggressive account I may put in up to 100%/day and get heavily leveraged using options. A more conservative account may max out at 15%-20% per day.

It’s unlikely anyone would have taken all of the trades with equal amounts, so personal results would vary greatly depending on the trader’s approach. Still, there was more than ample opportunity to take advantage of the Quantifiable Edges trade ideas in October. With all those caveats in mind, recent results are listed below and broken down by category. Since October was so unusual, I’ve also shown the September results below.


If you’d like a free 3-day trial of the Quantifiable Edges Subscriber Letter, just shoot an email to QuantEdges@HannaCapital.com and include your name and email address.

Saturday, May 31, 2008

Subscriber Letter Results For May

Below are the summary results for the trade ideas that were closed during the month of May. Results in May were above average in most areas.


A few notes:

The above results do not include currently open trade ideas.

All trade ideas come with specific entry and exit criteria and are tracked daily.

All trade ideas are in highly liquid stocks and ETF’s. The Quantifiable Edges Subscriber Letter does not deal with small caps.

All trade ideas are quantified through testing prior to entry. Subscribers may use the backtest results to help judge whether the idea may be appropriate for them.

This is not a performance report. I don’t know subscriber’s financial situations and risk tolerances. Therefore I do not suggest trade sizes.

There are essentially 3 kinds of trade ideas: 1) CBI trades, 2) System trades, and 3) Index trades.

For those that may be interested in the Index trades, they mostly use the S&P 500. All S&P index trades are entered using SPY. I don’t use leveraged etf’s like SDS or SSO to juice the performance numbers. Many times I will suggest scaling in to these trades in either 3 or 4 parts. Below are all SPY trade ideas that received fills since the 2/19/2008 inception:


If you’d like to either take advantage of Quantifiable Edges market timing, track the individual trades that construct CBI, or learn new systems (like this one) whose code is available for subscribers to download into Tradestation, you may want to give the Quantifiable Edges Subscriber Letter a look. For a free 3-day trial simply send an email with your name and email address to QuantEdges@HannaCapital.com For further information or to subscribe, click here.

Saturday, May 10, 2008

A Subscriber Letter Time Stretch System – And Some New Features

Nearly every trade idea tracked in the Quantifiable Edges Subscriber Letter is backed by a fully disclosed historically designed system. The systems all have specific entry and exit criteria and historical risk reward statistics are provided so subscribers can decide whether the trade idea may be appropriate for them. Here is an example from the 5/2/08 letter of a “time stretch” system that was used for gold (GLD):

GLD – buy @ $84.00. GLD has dropped sharply over the last several days. I am looking to buy based on the following criteria: 1)It has closed below its 10-day moving average for at least 10 days. 2) It is above its 200-day moving average. 3) It made its lowest low of the recent selloff today. 4) It closed stretched further below its 10-day moving average than it has on any day of the recent selloff.

Buying the next day at the setup day’s closing price and selling when it closed above the 5-period moving average would have produced the following results over the last 10 years in the list of 109 heavily traded ETF’s I track (most of which have not been around for 10 years):


The setup has only occurred once before in GLD – on June 14th, 2006. It was sold 2 days later for a 3.15% gain.

The trade idea was entered at the open on 5/2/08 @ $83.96. It was closed at the next session’s close (5/5/08) for $86.27 – a 2.75% gain.

Due to feedback from subscribers, I have now begun providing the code for any such system trades to the subscriber base. Tradestation users may import it right into their software for further testing and design.

The 2nd recently added subscriber desired feature is intraday updates. When notable action is occurring in open trades, I may send out Intraday Updates to subscribers alerting them.

If you haven’t trialed the Quantifiable Edges Subscriber Letter yet, just drop a note to QuantEdges@HannaCapital.com and receive three free days. Simply include your name and email address.

Tuesday, May 6, 2008

Quantifiable Edges Subscriber Letter April Results

I’ve presented below the summary results of the Quantifiable Edges Subscriber Letter trade ideas for April and since inception. April was a decent month. Although there were fewer trade ideas and rewards were a bit smaller than March, it was still strongly positive.


In addition to the trade ideas, the Subscriber Letter provides additional research beyond the blog and shows CBI analysis down to the sector level. More features will be announced soon. Should anyone wish to receive a free three-day trial to the Quantifiable Edges Subscriber Letter, just send an email to QuantEdges@HannaCapital.com and include your name and email address.